1Use a direct rollover
Ask the old plan to send the money straight to the new plan or IRA. A check made out to you means 20% is withheld for tax.
2The 60-day rule
If you do receive the money, you have 60 days to deposit the full amount into another plan or IRA to avoid tax.
3Why cashing out costs so much
The amount counts as income for the year, and before 59½ the IRS usually adds a 10% tax. Some exceptions apply.
Source: IRS
4Check what is vested
Only the vested part of your employer match moves with you. Your plan statement shows it.
How to do it in Oaktally
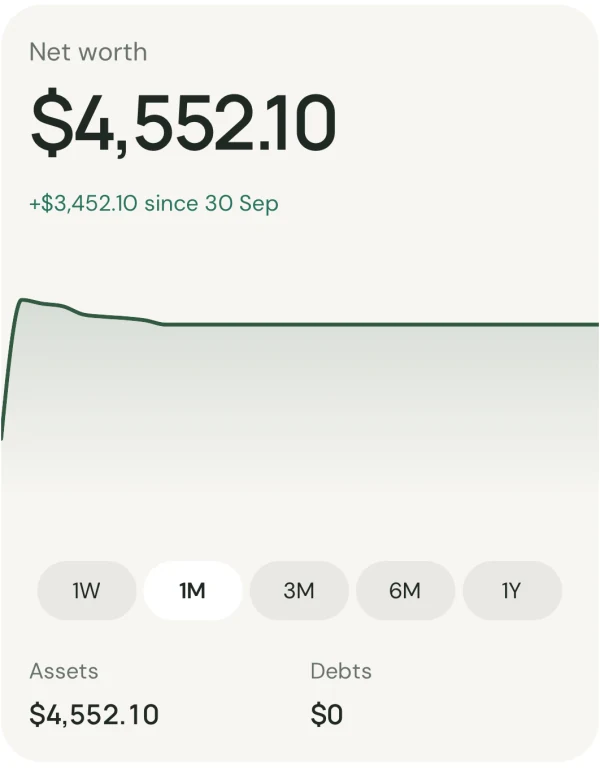
Old 401(k)s are easy to forget after a job change. Oaktally keeps every account, old and new, in one net worth.
- Add the accountAdd your 401(k) or IRA as an investment account with its current balance.
- Update it each statementUse Update balance when your statement arrives, so the number stays current.
- See it in your net worthHome counts it with your other accounts, so you see the whole picture.
Frequently asked questions
Can I leave my 401(k) with my old employer?
Usually, yes, if the balance is large enough. Check the plan's rules for small balances.
Should I roll a Roth 401(k) into a Roth IRA?
A Roth 401(k) rolls into a Roth IRA, keeping its Roth status. A traditional 401(k) rolls into a traditional IRA.
Further reading
IRS: Rollovers of retirement plan and IRA distributions ↗IRS: Tax rules on early withdrawals from retirement plans ↗IRS: Retirement topics, vesting ↗Educational examples, not individual financial advice.